

Stop letting bake-sale dollars earn 0.1%. PTAs, PTOs, and school booster clubs across the U.S. often keep fundraiser funds in basic bank accounts earning under 0.4% APY. It’s time to make those dollars work harder for students. A PTA high-yield savings account can boost your interest earnings dramatically without sacrificing safety or access. In this post, we’ll explore how the best high-yield savings account for PTAs, PTOs, and booster clubs – the Devote Savings Account – helps you earn materially higher interest (2.00% APY, variable) while keeping your money accessible and under your control. Every extra dollar earned in interest is a dollar that can fund field trips, instruments, uniforms without another fundraiser.
The Fundraising Gap: Dollars Sitting Idle in 0.1–0.4% Accounts
Most parent-teacher groups keep their money in standard checking or savings accounts that pay virtually nothing, often 0.1%–0.4% APY. At those sub-1% rates, your hard-raised funds are essentially sitting idle. By contrast, Devote’s high-yield savings account (HYSA) pays 2.00% APY (variable), which is about 5x the national average for savings (0.38% APY, FDIC national savings rate, October 19, 2026). That gap has real consequences for your budget:
Example 1: A typical PTA with $100,000 in reserve earns only about $300/year at 0.3% APY, but $2,000/year at 2.00% APY. That extra $1,700 could fund roughly five or six new teacher mini-grants or an entire grade’s science lab supplies.
Example 2: A larger district-wide booster club with $1 million idle at 0.3% earns just $3,000 annually, versus $20,000 at 2.00%. That’s an additional $17,000/year in “free” money, enough to purchase a full set of marching band uniforms or cover travel and lodging for a big competition.
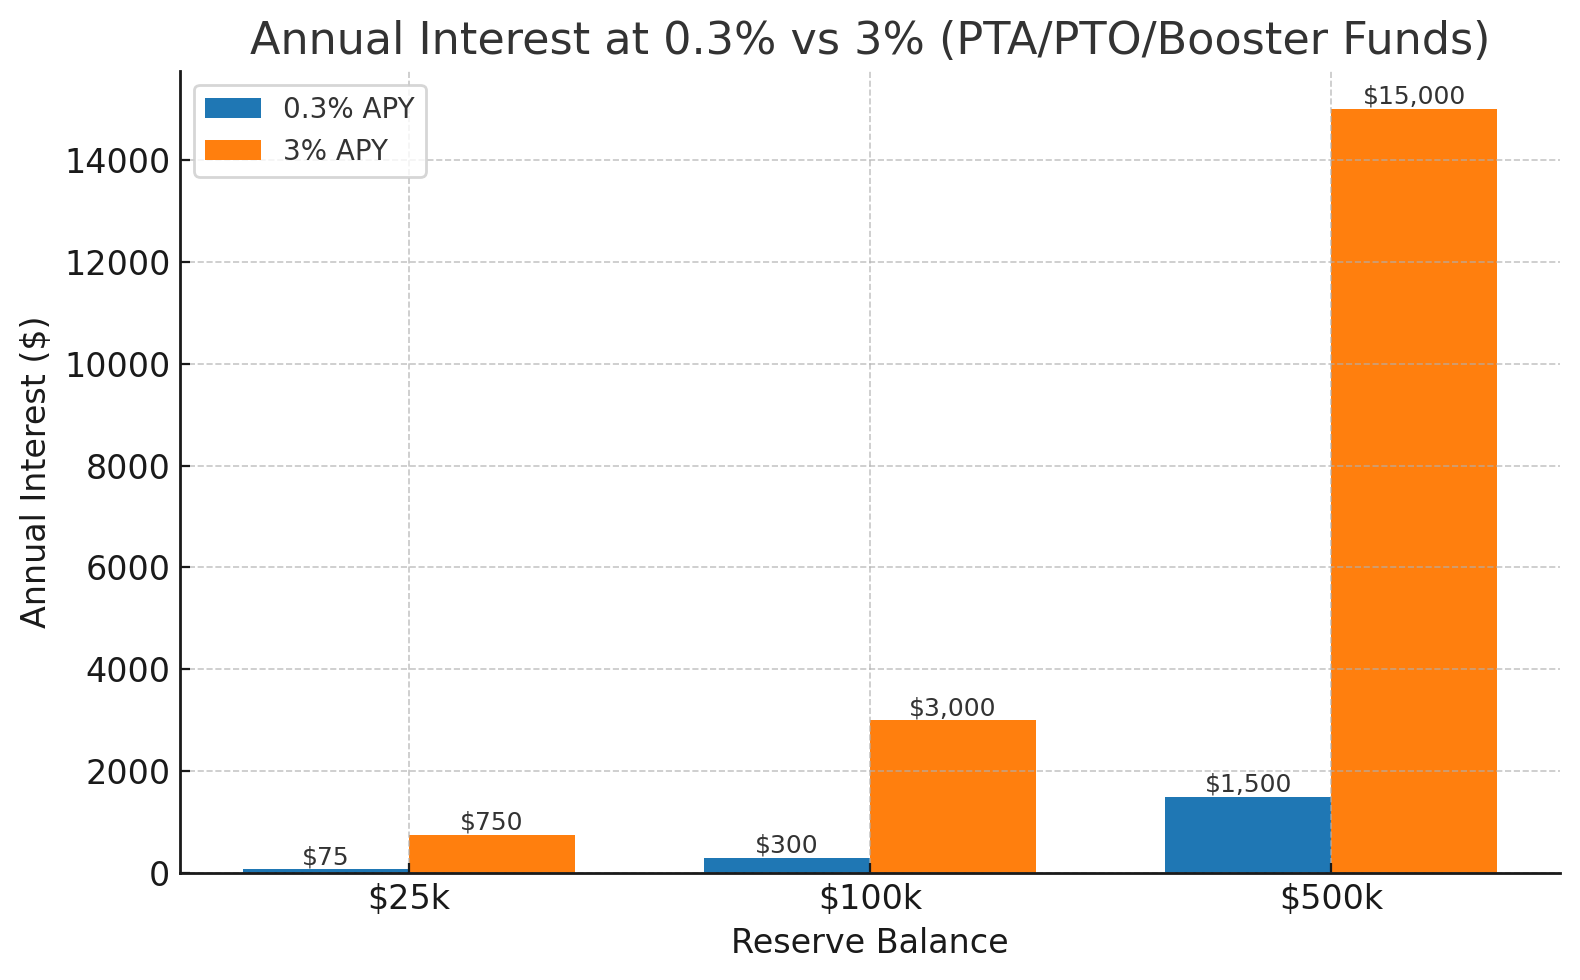
PTA high-yield savings interest comparison. Even a modest PTA reserve like $25,000 would earn only about $75 a year at 0.3% APY, versus $500 at 2.00% APY. Now picture larger booster budgets in the six figures – the lost interest from staying in a low-yield bank account quickly scales into the thousands of dollars.
The message is clear: every fundraiser dollar should be earning for you. In fact, nonprofits collectively forfeit billions in lost interest each year by sticking with near-zero accounts. Moving your PTO’s reserves into a high-yield, FDIC-insured account is one of the easiest ways to generate extra funds for students without any additional fundraising. It’s pure stewardship, making donor dollars go further in support of your mission.
School-Year Cash Cycles = You Need Yield and Liquidity
You might be thinking: “We can’t lock up our money, we need it accessible for expenses.” Absolutely. School organizations have seasonal cash flow and must balance earning interest with staying liquid. The good news is that with the right account, you can have both yield and liquidity.
Consider a typical school-year cycle: many groups collect a flood of cash in the fall (membership dues, fall fundraisers) and spring (galas, auctions). Between events, balances swell for months at a time before those funds are spent on programs. For example, you might raise $50,000 in the fall and not use it fully until well into spring – that’s money that could sit in a high-yield account earning interest during the interim. Conversely, during busy periods you have frequent outflows: pre-paying for field trip buses, sports tournaments, band travel, camp deposits, etc. Sometimes unexpected needs arise (a competition gets rescheduled or a vendor needs a rush payment). Liquidity is critical.
A specialized solution like Devote’s HYSA is built for this stop-and-go cash rhythm. You earn 2.00% APY on balances during the lull periods, and your funds stay accessible on a predictable timeline. There are no penalties, withdrawal fees or minimum term when you need money back. Withdrawals requested before 3 p.m. Eastern on a business day are processed that day, and the money typically reaches your linked checking account two business days later. (Need to pay the bus company next week for the choir trip? Request the transfer a few business days ahead and the money will be in your bank in time, with no interest penalty.) Keep enough in checking for anything due sooner, so students are never left waiting on that bus or hotel. You get the high yield and dependable access.
Equally important, Devote’s savings account has no minimum term and no withdrawal fees. You’re free to top up or draw down as your cash flow demands, without worrying about bank fees eating into your funds. The result is a school-friendly financial tool: you maximize interest earnings during the “idle” months, yet your money is available within a few business days for the next booster purchase. It’s yield without sacrificing control, the perfect fit for PTA/PTO and booster club cycles.
Buckets Honor Donor Intent & Simplify Audits
Every PTA/PTO treasurer knows the headache of tracking restricted funds and keeping donor-designated money separated. You might have booster bylaws or grant requirements that certain funds (like the playground fund or scholarship fund) not mix with general operating money. Too often, groups attempt this with messy spreadsheets or multiple bank accounts, which is error-prone and hard to hand off to the next volunteer. Devote solves this with “buckets”: separate funds within your savings account.
Think of buckets as digital envelopes for each purpose or program. You can create a bucket for Teacher Grants, Field Trips, Athletics Travel, Band/Choir, Robotics, Capital Improvements, Senior Gifts, or any category that matters to your group. Each bucket has its own nickname and balance. For example, if your bylaws say fundraising for the Playground Fund must be kept separate, simply make a “Playground” bucket and deposit those donations there. You’ll always see exactly how much is set aside for that purpose (down to the penny), with no commingling risk. Your general operating funds stay in their own bucket, untouched.
Why does this matter? Traditionally, treasurers used Excel or multiple bank accounts to simulate fund accounting. Anyone who’s tried that knows the pain, endless tabs, formulas, manual updates, and chances for error. One miscategorized expense or forgotten update can throw off your records. And when a new treasurer takes over, deciphering those spreadsheets (or juggling five separate bank accounts) is daunting. With Devote, it’s all in one secure platform: no complicated reclasses, no accidental overspending restricted money, and a seamless transition year to year.
Transparency and trust also skyrocket. If you raise $10,000 for the “8th Grade Trip,” parents can trust it’s in the 8th Grade Trip bucket, not accidentally spent elsewhere. In fact, Devote provides reports for the board that show each fund’s balance. At audit time, you can produce statements that clearly detail each sub-account’s activity and balance, making compliance a breeze.
Perhaps best of all, buckets save volunteer hours. Devote automatically tracks how much of your one big account belongs to each program, sparing you the tedious manual bookkeeping. For a volunteer-run PTA, less time on tedious accounting means more time you can spend organizing events or with your family instead of being stuck in “Excel hell”. Devote gives you the clarity of separate accounts with the convenience of one platform, plus interest earnings on every dollar (yes, even money sitting in the “Field Trip” bucket accrues interest until it’s used).
Why Devote Beats a Traditional Bank for PTAs/PTOs/Boosters
At this point, you might wonder: Why not just find a better rate at a regular bank or credit union? The reality is, traditional banks aren’t built for the unique needs of volunteer-run school groups. Devote is. It’s a financial platform designed exclusively for nonprofits (parent groups, booster clubs, churches, charities) – which means it addresses pain points that generic banks often ignore. Here’s how Devote outshines a typical bank for PTA/PTO and booster club finances:
Much Higher Interest: Devote offers 2.00% APY (variable) on all deposits, about 5x the national average for savings. Most banks offer near-zero rates to small organizations, many PTAs are stuck at 0.1%–0.2% today. With Devote, your reserves actively grow. It’s like earning an annual grant without any extra work. In short, 2.00% vs 0.2% is the difference between your money at work versus parked in neutral.
Federal Deposit Insurance (Up to $50 Million per EIN): Typical banks only insure up to $250,000 per account, fine for a small PTA, but larger booster programs or combined district funds can exceed that, leaving money at risk. Devote solves this by spreading deposits across a network of FDIC-insured banks and NCUA-insured credit unions, for federal deposit insurance up to $50 million per tax ID. Your funds are spread across those institutions behind the scenes, so even the largest booster club or education foundation can keep every penny federally insured. This 200× higher coverage provides peace of mind to boards and school districts alike. (Try asking a big bank to insure $5 million for your band booster in one account; with Devote, that balance can be federally insured.)
Separate Fund “Buckets” at No Cost: Unlike a regular bank, Devote lets you separate money into funds for free. No need to actually open multiple accounts or meet multiple minimum balances. However many funds you track, they’re all neatly organized under one login. This built-in fund accounting means zero extra fees or hassle to track restricted donations, a huge win for transparency and audit readiness. (Many banks would make you open separate savings accounts, and maybe charge fees on each, if you wanted to mimic this.) With Devote, you can add a labeled bucket whenever you launch a new fundraiser or program.
QuickBooks Sync & Approval Rules: Devote isn’t just a savings account. It syncs with QuickBooks, saving you from manual data entry, and produces reports for the board. Approval rules let you require a second person to approve transfers, a useful check for volunteer-run groups. In practice, Devote can streamline the monthly close for your PTA.
Predictable Transfers (No Penalties): Devote knows you need to plan around when money arrives. Withdrawals requested before 3 p.m. Eastern on a business day are processed that day, and the money typically reaches your regular checking account two business days later. So if the school asks the PTO to pay for new Chromebooks next week, you can pull the needed amount from your high-yield reserve in time. There are no withdrawal penalties or fees and no minimum term. For “uh-oh, we need funds ASAP” moments, keep a cushion in checking.
Zero Fees & No Minimum Term: As volunteer-led groups, we hate seeing fundraising dollars wasted on bank fees. Devote was built with that in mind: no monthly fees, no maintenance charges, no transfer fees, and no hidden fees at all. There’s no minimum term, either. In contrast, many business bank accounts charge $10–$25 a month or require hefty balances to waive fees, money that should be going to your programs, not the bank’s profits. With Devote, every dollar stays committed to your mission. Transparency is core to Devote’s ethos, so you won’t get nickel-and-dimed.
Built for Easy Oversight & Transitions: Devote’s platform was built for nonprofits, where oversight and continuity matter for groups with rotating officers. The account supports roles, so your president, treasurer, finance committee, or school bookkeeper can each have appropriate access. No more sharing one login or feeling like only the treasurer can see “the books.” This makes year-end audits and board reviews far more comfortable – everyone can have transparency. Moreover, when officers change, adding the new treasurer (and removing the old) is simple, avoiding the notorious hassle of changing bank signatories (which often requires all new officers to visit a branch in person). Devote has anticipated those needs and made the interface super user-friendly. The result is an account that is volunteer-proof: it stays consistent and secure through leadership changes, and you’ll never have to “re-explain” to a clueless bank why you need multiple subaccounts or multiple users. Devote speaks PTA/PTSA language out of the box.
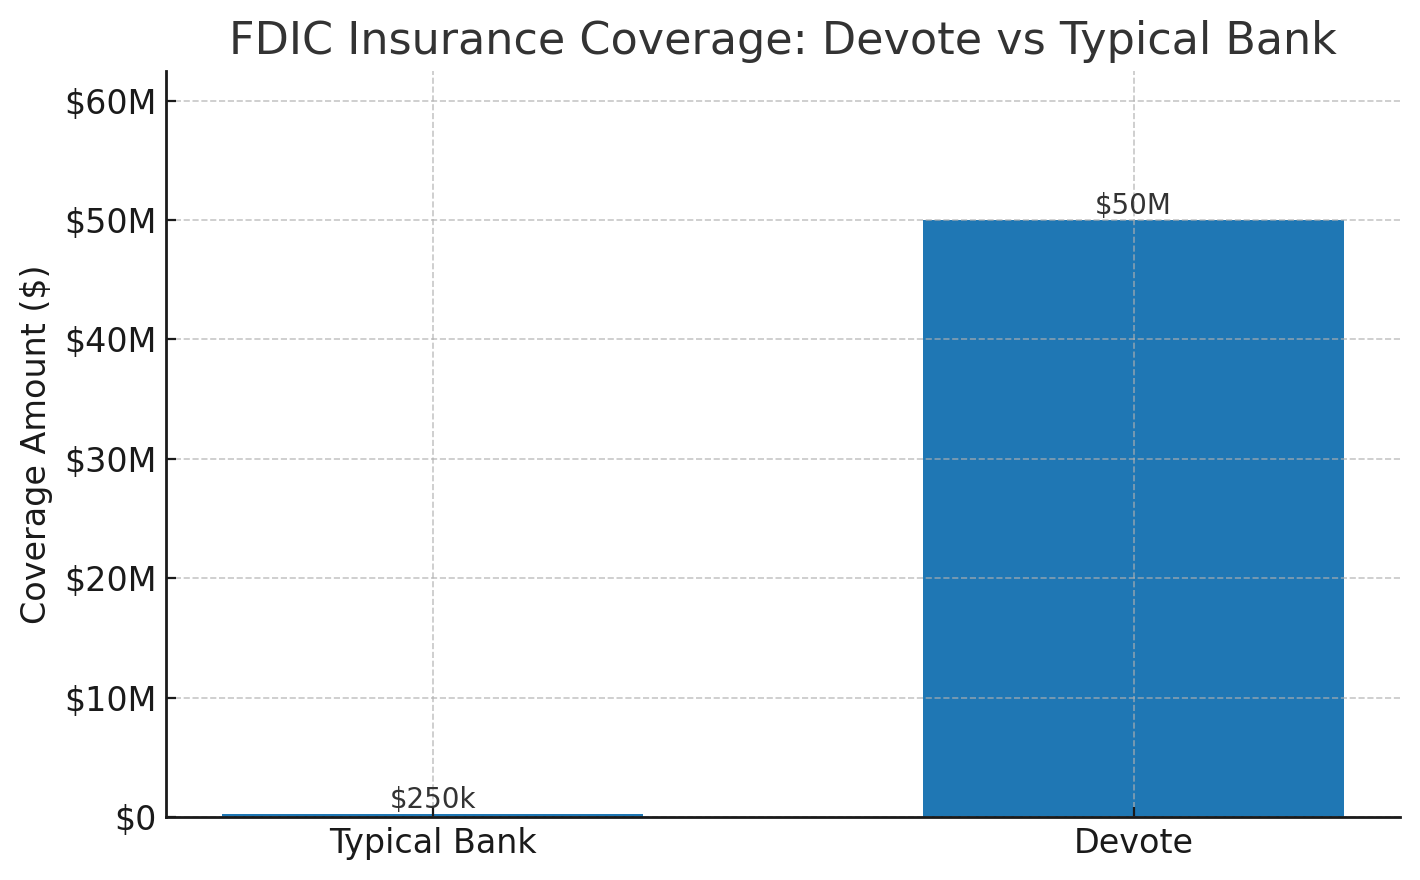
Comparison of Devote’s nonprofit HYSA vs. typical bank. Devote offers 2.00% APY (about 5x the national average of 0.38%) and federal deposit insurance up to $50 M (200× the standard $250k cap). This higher yield and coverage mean booster clubs can significantly grow funds without sacrificing security.
In short, Devote delivers the best of both worlds for school organizations: top-tier financial returns and nonprofit-tailored features. It’s not just “another bank account”, it’s a holistic solution to make your treasurer duties easier and your fundraiser dollars mightier.
Common Concerns, Addressed: We know any change can raise questions. Here are a few common objections PTA/PTO leaders have and how Devote addresses them:
“Will our district approve an online account like this?” – Deposits are federally insured up to $50 million per tax ID, and Devote provides transparent, auditable records. You can give district officials or principals access through roles if needed to satisfy any oversight requirements. When every penny is federally insured and trackable, that conversation is easier.
“What if we need funds quickly?” – Withdrawals requested before 3 p.m. Eastern on a business day are processed that day, and the money typically reaches your school checking account two business days later. There are no penalties, withdrawal fees or minimum term. For bills due sooner than that, keep a cushion in checking and plan larger payments a few days ahead.
“Can we track restricted funds easily?” – Absolutely. Devote’s separate funds allow precise tracking of each fundraiser or grant. You’ll know exactly how much is in the “Drama Club Trip” bucket or the “STEM Grant” bucket at all times. This granularity actually exceeds the tracking capability most PTAs have today, making your finance reports crystal clear. No more commingling or guesswork.
Next Steps: Put Your Fundraiser Dollars to Work
You’ve worked hard to raise these funds, now let’s make them work hard for you. With Devote’s high-yield savings account, you can earn more for your students without any extra fundraising. It’s a safe, simple way to stretch every dollar further in support of your school.
Ready to see how much more your PTA/PTO could be earning? [Calculate Your PTA’s Lost Interest] (use our free calculator tool) by plugging in your average bank balance and current rate. You might be shocked at the annual interest you’re leaving on the table. Often, it’s enough to fund an extra field trip or a new set of laptops each year with zero additional bake sales. This eye-opening number can help convince your board that it’s time for a change.
Make the Switch: When you’re ready, opening a Devote High-Yield Savings Account is simple: you apply online with your organization’s EIN, address and the controlling party’s details. There’s no branch visit required. Once opened, you’ll transfer in your funds, set up any desired buckets, and start earning interest. Devote’s team is there to assist with any questions.
Bottom line: You owe it to your students to make every dollar count. By upgrading your PTA or booster club’s banking to a high-yield, high-insurance solution like Devote, you’re practicing smart stewardship and unlocking funds that were hiding in plain sight. It’s free money for your mission. No new fundraiser, no extra volunteer hours. Just a better home for your hard-earned reserves.
🔒 Federally Insured up to $50 Million 🚀 2.00% APY – About 5x the National Average 💸 No Withdrawal Fees or Penalties 🗂️ Separate Fund “Buckets” 📊 QuickBooks Integration
Ready to put those idle dollars to work for your school? Open a Devote High-Yield Savings Account and watch your fundraiser dollars grow for the kids.
FAQ
Q: What happens if interest rates change?
A: Devote’s APY is variable, so it can change at any time. The current rate is 2.00% APY. If general rates rise or fall, Devote’s rate may move too.Q: How can Devote insure up to $50 million? Is that legit?
A: Yes. Devote spreads deposits across a network of FDIC-insured banks and NCUA-insured credit unions through our deposit program partner. Each institution provides up to $250k of federal insurance, all under your PTA’s tax ID, for coverage up to $50 million. You still see one combined account balance, but behind the scenes your funds are spread out to stay fully insured. It’s a common practice (used by many large cash management programs), Devote just brings it to nonprofits. You get a single statement and interface, and federal deposit insurance on every dollar up to $50 million.Q: How long does it take to open and set up?
A: You apply online. The application will ask for your organization’s EIN, address and the controlling party’s details. Once approved, you fund the account by transfer from your bank. Setting up buckets is simple: you create and name each fund in the app.Q: How do we handle adding new officers or changing account signers?
A: Devote allows multiple users with roles, so you can add a new treasurer or finance chair in the app. You can give auditors or district officials access if needed, and remove access for former officers. This role-based access and easy user management make year-to-year transitions smooth and ensure financial continuity despite volunteer turnover.Q: Our PTO has checking at a local bank. Do we need to close it?
A: Not at all. Devote’s savings account can work alongside your existing checking account. In fact, that’s recommended: use Devote to hold your reserves and longer-term funds (earning high interest), and transfer funds to your regular checking as needed for writing checks/debit use. Many groups keep a few thousand in checking for immediate expenses and park the rest in Devote to grow. Think of Devote as your high-yield reserve account, complementing (not necessarily replacing) your day-to-day bank.
Now’s the time to stop leaving money on the table. By switching to a purpose-built PTA high-yield savings account like Devote, you transform idle dollars into active support for your students and teachers. It’s safe, smart, and simple. A win-win for your school community. Here’s to making every fundraiser dollar work harder for our kids!
Extra you earn with Devote annually$0
*Rates as of October 19 2026. Devote APY is variable and may change at any time.
**Demo assumes 365 days; National‑average rate is the
FDIC national savings rate.
Put your PTA's reserves to work. Devote Savings pays 2.00% APY (variable), and up to $50 million per tax ID is federally insured across a network of FDIC-insured banks and NCUA-insured credit unions. No account fees and no minimum term. The application takes about 10 minutes.
